
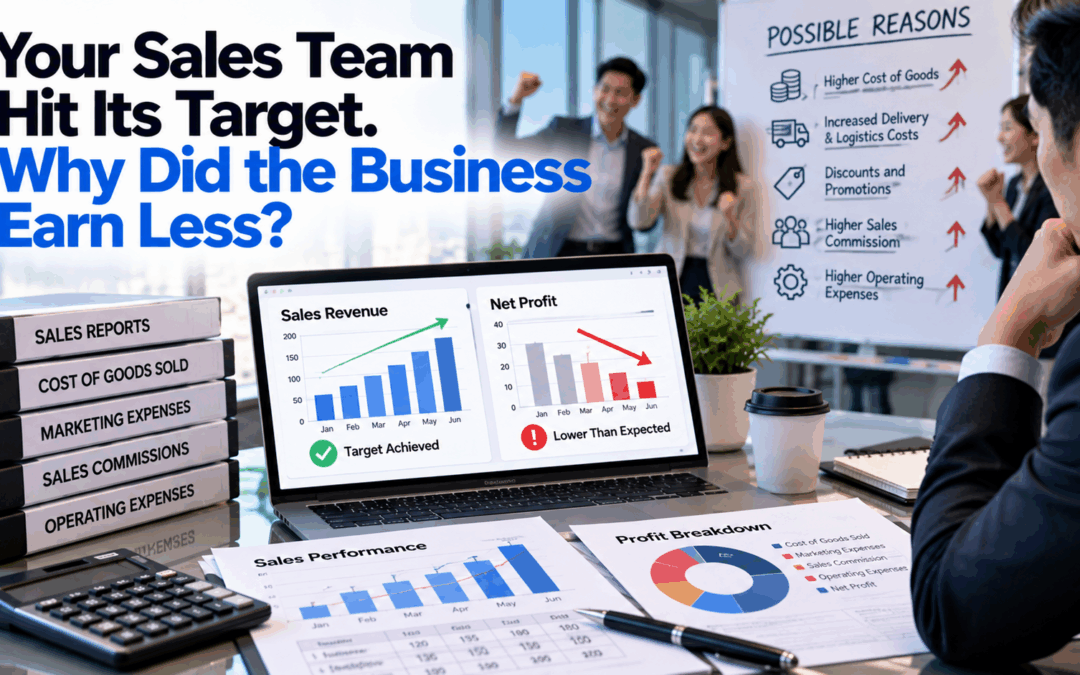
The monthly sales report looks encouraging. The team has exceeded its target, several large orders have been secured, and the warehouse has been busier than usual. Management congratulates everyone and starts discussing a higher target for the next quarter.
Then the accounts arrive. Revenue has increased, but operating profit has fallen. The business has processed more orders, handled more deliveries and paid more commissions, yet less money remains after expenses.
For a business owner, this can be difficult to reconcile. If everyone has worked harder and customers have bought more, why has the financial result weakened?
The answer often lies in the details behind the sales total. Discounts, the products sold, delivery promises and the resources needed to fulfil orders can all change what the business earns. Before increasing the next target, management needs to understand what the latest sales actually contributed.
Start with the Gap Between Sales and Profit
Revenue measures the value of sales recognised in the accounts. It does not show how much remains after the business pays for the goods, services and operating resources used to generate those sales.
Consider a hypothetical distributor comparing two months. In the first month, revenue is S$200,000 and cost of sales is S$140,000, leaving gross profit of S$60,000. Operating expenses of S$40,000 leave operating profit of S$20,000.
In the following month, revenue rises to S$240,000. However, cost of sales reaches S$180,000, so gross profit remains S$60,000. Operating expenses increase to S$48,000, leaving operating profit of S$12,000.
In this simplified example, sales have grown by 20%, while operating profit has fallen by 40%. The figures exclude finance costs and tax. The business has generated more activity without increasing gross profit, then incurred additional operating expenses to support that activity.
This comparison gives management two separate questions to investigate: why the extra revenue produced no additional gross profit, and why operating expenses increased.
Check How Much Discounting Helped Achieve the Target
Discounts can help secure orders, clear selected stock or support a deliberate commercial strategy. However, their effect on profit can be much larger than their percentage suggests.
Assume a product sells for S$100 and costs S$70 to purchase. Before considering other costs, the gross profit is S$30 per unit. A 10% discount reduces the selling price to S$90, leaving gross profit of S$20.
The selling price has fallen by 10%, but gross profit per unit has fallen by one-third. To produce the same S$3,000 gross profit previously earned from selling 100 units, the business would need to sell 150 units at the discounted price, assuming the purchase cost remains unchanged.
That calculation does not include additional handling, delivery or commission costs. If those rise with volume, selling 150 units may still leave the business worse off overall.
Review the actual selling prices achieved, particularly near the end of the target period. If discounts regularly become larger in the final week, investigate whether the target encourages employees to prioritise closing orders over preserving earnings.
Look at Which Products Customers Bought
Two months with similar revenue can produce very different profits because customers bought different combinations of products.
A distributor might sell both standard consumables and specialist accessories. A large order for consumables could push revenue above target while contributing less gross profit per sales dollar than the accessories that usually make up a greater share of business.
Compare revenue and gross profit by product category. Identify whether growth came from products with stronger margins, thinner margins or unusually high fulfilment requirements. A single overall percentage can conceal meaningful changes within the business.
This does not mean every lower-margin product should be removed. Some products support repeat purchases, help win broader customer relationships or sell efficiently in large quantities. Assess those benefits using actual order patterns rather than assuming that a large sale will eventually generate more profitable business.
The useful question is whether the changing product mix supports the company’s earnings objectives and available capacity.
Follow the Promises Made to Win the Order
The invoice price may tell only part of the story. A salesperson may secure an order by offering several deliveries, urgent dispatch, customised packaging or additional support.
Those promises can create work that is not visible in the sales report. Warehouse staff may pick the same order in stages, drivers may make extra trips, and customer service employees may spend time coordinating special arrangements.
Review a sample of large or unusually demanding orders with operations. Compare what was quoted with what was actually required to fulfil the order. Look for services that were provided without a charge or without being considered when the price was approved.
Some additional service may be commercially justified. The aim is to make its cost visible so that management can price future orders more accurately, set clearer service limits or approve exceptions consciously.
A customer requesting five separate deliveries is buying a different service experience from one accepting a single consolidated shipment, even when the product quantities are identical.
Separate Useful Extra Business from Expensive Extra Activity
Gross profit is a useful starting point, but management may also need to examine contribution. Contribution is revenue less variable costs, leaving an amount to cover fixed costs and profit.
For an individual order, relevant variable costs might include purchased goods, order-linked commissions and incremental delivery charges. Define the calculation consistently and avoid counting a cost twice if it is already included elsewhere.
Keep this analysis distinct from an allocation of every company expense to each order. An arbitrary share of office rent may not help decide whether a small additional order is worthwhile when spare capacity exists. However, a growing stream of orders that requires another vehicle, additional staff or more warehouse space creates a broader capacity decision.
Operations can help identify when the business crossed that threshold. Perhaps the new volume required weekend shifts or regular outsourced deliveries. What appeared to be modest growth may have triggered a noticeable increase in costs.
Management needs to understand both the immediate economics of orders and the resources required to sustain the higher activity level.
Review What the Commission Scheme Rewards
If commission depends entirely on sales value, employees have a clear reason to pursue revenue. They may receive the same reward for a straightforward, profitable order as for one secured through a substantial discount and expensive service commitments.
That does not mean the sales team has acted improperly. Employees may simply be responding to the targets and incentives management established.
Review whether the scheme reflects the business’s commercial priorities. Depending on the circumstances, management might consider gross profit, approved pricing, customer retention or a combination of measures. Any calculation should be clear enough for employees to understand and check.
Avoid replacing a simple revenue target with a complicated formula that nobody trusts. Cost information must be reliable, and employees should understand which outcomes they can influence. A salesperson should not be held responsible for unexplained cost allocations or operational decisions outside their control.
Evaluate proposed changes using past orders before introducing them. Follow existing employment and commission terms when implementing changes, rather than retrospectively altering rewards already earned.
Check That Sales and Finance Are Measuring the Same Thing
Sometimes the apparent contradiction begins with different definitions. The sales dashboard may count orders booked, while the accounts report revenue recognised for the period. Other reports may show invoices raised or cash collected.
These measures answer different questions. An order secured this month may be delivered later. An invoice may subsequently be reduced by a credit note. A receipt may settle a sale recorded in an earlier period.
Before assessing performance, establish what the target measures and reconcile it with the financial report. Confirm whether discounts, cancellations and returns are included consistently.
A short reconciliation can explain how the team’s reported achievement connects to the accounts. It should show the material differences in plain language, so managers can distinguish timing issues from weaker commercial performance.
Without that shared understanding, sales may defend a target it genuinely achieved while finance discusses a different set of transactions.
Do Not Attribute Every Profit Decline to Sales
Higher revenue and lower profit occurring together do not prove that the additional sales caused the decline. Other costs or events may explain some of the movement.
The business may have hired staff ahead of expansion, incurred repair costs, recognised an inventory adjustment or paid for a marketing campaign. These items deserve their own explanation rather than being absorbed into a general conclusion that the sales team sold badly.
Ask finance to break down the movement from the previous period’s operating profit to the current result. Identify the effect of revenue growth, changes in gross margin and significant expense movements.
Separate recurring changes from unusual items. A permanent increase in delivery costs requires a different response from a one-off repair. Likewise, an investment intended to support future growth should be assessed against its plan, while still recognising its effect on current profit.
This creates a fairer discussion and directs action towards the causes management can address.
Build a Sales Review That Includes Earnings
A useful monthly review should let management see both sales achievement and the financial result behind it. Start with a small set of reliable measures rather than a large dashboard filled with estimates.
Alongside revenue, review gross profit in dollars and as a percentage of revenue. Add information on material discounts, major product categories and significant fulfilment costs. Where practical, examine unusual customer or order patterns.
Gross profit dollars and percentages should be considered together. A lower percentage does not automatically mean a worse outcome if total profit contribution improves. Equally, an attractive percentage on a small amount of business may not generate enough to support operating costs.
Use the review to select specific actions. For example, management could introduce approval for discounts below an agreed threshold, price split deliveries separately or revise quotations for products requiring extensive support.
Assign responsibility and check the result in the next reporting period. The value of the review comes from connecting financial information to decisions about how the business sells and delivers.
Set the Next Target with a Clearer View of Success
A revenue target gives the team direction, but it should sit within a broader understanding of the business’s earnings requirements. Before raising it, review what the company would need to sell, at what prices and with what resources to achieve the intended result.
Sales, operations and finance each contribute part of that assessment. Sales understands customer expectations, operations knows the work required, and finance can bring the financial effects together.
Royal Premier provides accounting and bookkeeping services, including management accounts, that can support businesses in reviewing their financial performance. Clear, consistent records make it easier to identify whether growth is producing stronger earnings or simply more activity.
When the sales team next exceeds its target, management should be able to explain what drove the achievement and what it meant for profit. That gives the business a sounder basis for recognising performance, adjusting incentives and deciding which opportunities to pursue next.
Recent Comments