
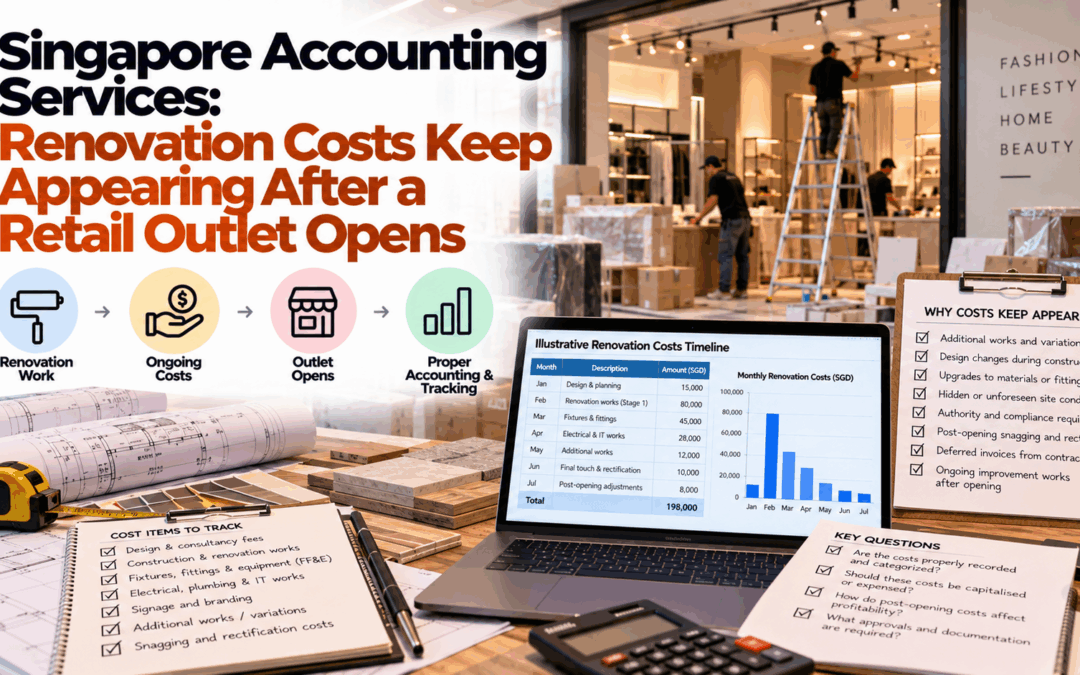
The doors are open, customers are browsing, and the store manager has started tracking daily sales. Then another contractor invoice arrives. A week later, the electrician submits a final claim, the signage supplier requests payment, and the owner approves additional shelving after seeing how customers move through the shop.
For a retailer, opening day rarely marks the end of every renovation-related payment. However, the invoices arriving afterwards may represent very different things: work completed before opening, new improvements, repairs or operating expenses. Recording them all under “renovation” makes it difficult to understand both the investment in the outlet and its trading performance.
Royal Premier provides accounting, bookkeeping and management reporting services. For retailers exploring Singapore accounting services, a useful starting point is bringing the renovation records and operating accounts together. Each late bill should have a clear explanation of what was supplied, when it was supplied and how it belongs in the accounts.
Opening Day Does Not Determine Every Accounting Entry
The date an invoice reaches finance is not necessarily the date the underlying cost arose. A contractor may submit a final invoice several weeks after completing the work. Conversely, a supplier may issue an advance invoice before delivering anything.
Start with the underlying activity. Identify whether the charge relates to completed installation, materials received, future work or a new request made after trading began. The invoice date is part of the evidence, but it cannot answer all these questions.
A simple project timeline helps. Record major installation dates, handover, when equipment became usable and subsequent changes. This gives finance a basis for discussing late invoices with the project team instead of classifying them solely by whether they arrived before or after opening.
Break Down the Renovation Package
A contractor’s final invoice may combine several types of expenditure. Display fixtures, electrical installation, routine cleaning and launch decorations can appear under one project reference even though their accounting treatment may differ.
Under property, plant and equipment principles, qualifying asset costs include expenditure directly attributable to preparing an asset for its intended use. General opening activities do not automatically qualify. Routine servicing is normally expensed, while subsequent additions or replacements require their own assessment.
Request a breakdown where the invoice description is too broad. The original quotation, approved variations and contractor schedules may provide enough information to distinguish the elements. Where an allocation is necessary, document a reasonable basis rather than assigning the entire package to whichever account is most convenient.
The purpose is not to create unnecessary detail for every small item. It is to ensure that material amounts are supported and that the same approach is applied consistently across outlets.
Recognise Work Received Even When Billing Is Delayed
At month-end, finance should ask whether the retailer has received work or goods for which an invoice remains outstanding. Waiting for the supplier’s final paperwork can leave both assets or expenses and related liabilities understated.
Consider a hypothetical shop that opens on 20 November. Before the November accounts are prepared, the project manager confirms that an electrical installation was completed and accepted before opening. The agreed value is S$18,000, but the invoice will not arrive until December.
Assuming the obligation and amount are supported, the November accounts should reflect the installation and corresponding liability under the appropriate classification. Its status as a qualifying asset cost or expense needs separate assessment. The missing invoice does not, by itself, justify omitting it.
When the December invoice arrives, match it to the amount already recorded. Otherwise, finance may record the same expenditure twice. Any difference should be investigated and handled according to its cause rather than automatically charged as a new December cost.
Use a Project Schedule to Explain the Remaining Balance
A renovation schedule should distinguish the original contract, approved variations, work received, invoices recorded, payments made and amounts still expected. Those figures answer different questions and should not be combined into one “outstanding renovation” total.
For example, an unpaid invoice is different from a commitment for work that has not started. An advance already paid is different from work received but not yet billed. Keeping those categories separate helps management understand both the accounting position and the remaining cash requirement.
Reconcile supplier advances against later claims. A deposit can remain in the accounts incorrectly if the final invoice is recorded without applying it. Equally, paying a final claim without checking earlier payments can create an overpayment.
The schedule should also show who is following up each unresolved item. A balance described only as “pending contractor” can remain untouched for months unless someone has responsibility for obtaining the missing information.
Start Depreciation From the Relevant Available-for-Use Date
Depreciation generally begins when an asset is in the location and condition needed to operate as management intends. It does not wait for the last supplier payment, final invoice or achievement of the outlet’s sales target.
The opening date may provide useful evidence, but different assets can become available at different times. Record the relevant dates and supporting handover information rather than leaving every item in construction in progress until the entire project file is closed.
Late invoices may require the recorded asset cost and related depreciation to be reviewed. Finance should assess the circumstances, including whether the amount was already accrued. A delayed invoice is not a reason to postpone reviewing the asset register.
Distinguish New Improvements From Ongoing Repairs
Once customers start using the outlet, management may discover changes it wants to make. Extra display units, replacement lighting and repairs to a damaged fitting should each be reviewed according to their substance.
Ask what the expenditure achieved. Did it create a new asset, replace a significant component or maintain an existing item? The fact that the same renovation contractor carried out the work does not establish its classification.
Keep the post-opening request and approval with the invoice. This helps distinguish a new instruction from an omitted part of the original contract. It also shows whether the expenditure was expected in the opening budget or represents an additional management decision.
Where an existing component is replaced, finance should consider whether its recorded carrying amount needs removal. Adding every replacement to the asset register without reviewing what has been taken out can leave the records showing items no longer in use.
Keep Defects and Contractor Recoveries Separate
An outlet may open with a list of defects still to be addressed. The retailer might ask the original contractor to return, withhold an agreed amount or appoint another supplier to complete urgent remedial work. Each situation needs supporting records.
Maintain a defects register showing the issue, responsible party, proposed action and current status. If the retailer expects reimbursement, retain the correspondence supporting that expectation. Do not automatically assume the cost of another contractor can be recovered in full.
Retentions also need clear records. Money withheld from payment does not necessarily mean the underlying obligation disappears. The contract and work performed need to be considered when determining the balance.
For management reporting, separate the cost incurred from any expected recovery. Combining them too early can hide the amount at risk and make the project appear settled before the contractor has agreed to anything.
Review Late Information Carefully Around Year-End
A late invoice becomes particularly important when it arrives after the financial year-end. The question is whether it provides evidence about a condition that already existed at the reporting date or relates to something that arose later.
Under subsequent-events principles, evidence of an existing year-end condition may require an adjustment before the financial statements are authorised. New events are assessed differently, including whether material disclosure is needed. The invoice’s arrival date alone does not determine the outcome.
Compare the invoice with completion records, correspondence and any accrual already recorded. Explain the conclusion in the year-end file. If the financial statements have already been authorised, obtain the appropriate accounting assessment rather than assuming the same adjustment process still applies.
This review is more efficient when the project schedule identifies expected final claims before year-end. Finance can then follow up known gaps instead of discovering the exposure only when suppliers request payment.
Show Outlet Performance Without Hiding Costs
Late renovation bills can make a new outlet’s monthly results difficult to interpret. One month may appear unusually strong because obligations were omitted, while the next looks weak because several old invoices were charged together.
Accurate timing and classification come first. Management reporting can then explain opening-related expenses separately from recurring trading costs where that distinction is useful. Depreciation and other relevant charges should remain visible rather than being excluded simply to present a more attractive result.
Royal Premier’s management reporting services include financial analyses, variance reports and forecasts. These can support a clearer discussion of whether a variance comes from trading, an additional project decision or a correction to earlier records.
The owner should be able to see the reported result and understand any supplementary performance measure. If a report presents an adjusted view, show how it reconciles to the accounts and identify the exclusions consistently.
Keep the Cash Forecast Open After Launch
Even when renovation costs are recorded correctly, the payments may continue for several months. Final claims, retained amounts and later improvements can place pressure on cash while the outlet is still building its customer base.
Prepare a payment schedule that distinguishes agreed amounts, estimates and disputed claims. Include expected settlement dates and update them as information changes. A project marked “completed” in an operational report should not automatically disappear from the cash forecast.
Compare these payments with the outlet’s other needs, including stock replenishment, payroll and rent. Strong opening-week sales may not provide enough cash to absorb all remaining project bills comfortably.
Management also needs to know which expenditure remains optional. A new display feature that has not been ordered presents a different decision from an accepted final claim. That distinction helps the owner prioritise spending without confusing cash planning with the recognition of existing obligations.
Make Singapore Accounting Services Part of the Project Handover
A handover to operations should include a handover to finance. Provide the approved budget, supplier list, contracts, variations, payment history and outstanding claims, together with information about the assets installed.
Create an asset register that identifies significant items, their location, cost and available-for-use dates. Preserve invoices and allocation schedules so the recorded values can be explained later. Appropriate useful lives and residual values should be reviewed rather than assumed from one standard setting for every item.
Assign a deadline for closing the main project records, with an exceptions list for matters that genuinely remain unresolved. Closing the file should mean that balances are explained and responsibilities assigned, not that unfinished questions have been moved into a miscellaneous account.
For retailers using Singapore accounting services, this process gives the accounting team the information needed to maintain records as the outlet moves from construction to normal operations. It also makes future repairs, replacements and refurbishments easier to trace.
Use the Final Cost Review Before Opening Another Outlet
Once the major claims are resolved, compare the original budget with the final project position. Separate genuine scope additions from price changes, omitted estimates and remedial work. Each cause suggests a different improvement for the next opening.
A budget overrun caused by repeated layout changes needs a different response from one caused by invoices that were simply recorded late. The first concerns project decisions; the second concerns reporting and communication. Combining them into one variance obscures the lesson.
Retain the review as a planning reference, while recognising that the next outlet may have different premises and requirements. Reliable historical figures are useful when their scope and limitations are understood.
This also helps management evaluate the investment more honestly. The cost of opening an outlet should not remain a moving target solely because information was never brought together.
Close the Project Without Losing Sight of the Outlet
Renovation invoices arriving after opening are not automatically a problem. The difficulty arises when the retailer cannot explain whether they relate to earlier work, new assets, repairs or future commitments. That uncertainty affects financial reporting, cash planning and the assessment of the outlet’s performance.
Review the remaining claims, reconcile advances, update the asset records and establish a clear schedule for settlement. Keep project expenditure distinguishable from recurring operations while ensuring the accounts include all relevant costs and obligations.
Speak with Royal Premier about its Singapore accounting services, bookkeeping and management reporting support. With a documented project handover and consistent records, management can move beyond chasing late invoices and focus on how the new outlet is performing.
Recent Comments