
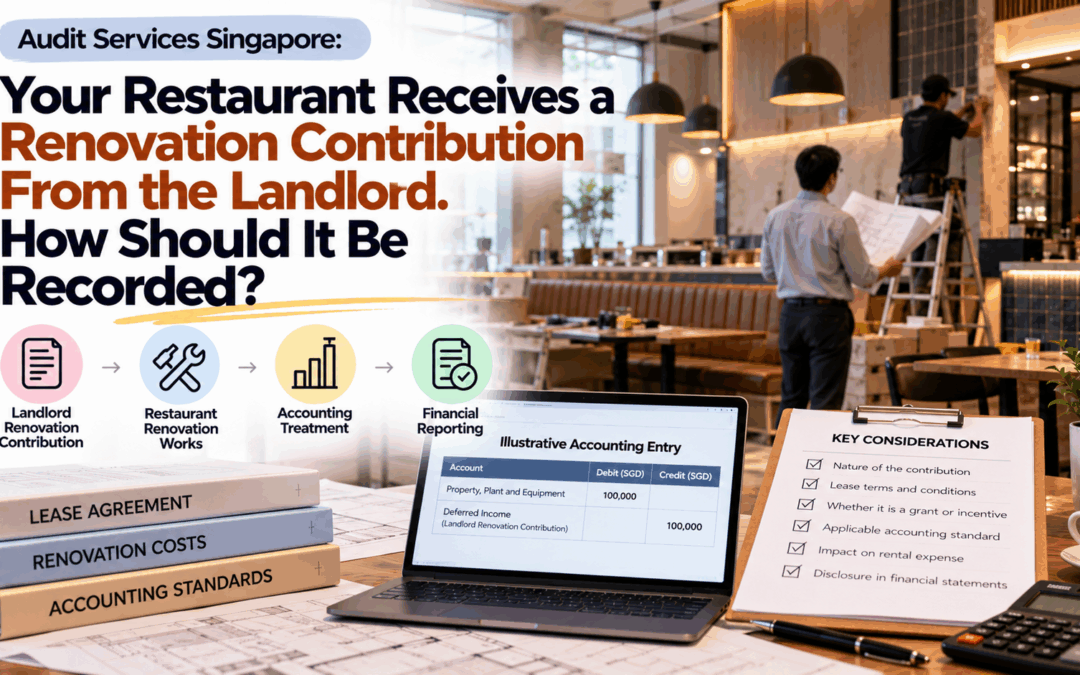
Your restaurant has secured a new location, and the landlord agrees to contribute towards the renovation. The payment helps fund the kitchen, dining area and other work needed before opening. When the money arrives, the finance team needs to decide where it belongs in the accounts.
Should it be recorded as other income? Should it reduce the renovation asset? Or should it form part of the lease accounting?
The answer depends on the substance of the arrangement. A landlord’s contribution towards the restaurant’s own fit-out may be a lease incentive, while payment for work carried out on the landlord’s behalf could require a different assessment. The description on the bank transfer does not settle the question.
For restaurant owners considering auditing services Singapore providers offer, the useful starting point is to bring the lease, contribution agreement and renovation records together. These documents explain what the payment funds and which accounting treatment is appropriate.
Identify What the Landlord Has Agreed to Fund
A renovation contribution can take several forms. The landlord might pay a fixed amount when the lease begins, reimburse specified invoices or pay a contractor directly. Another arrangement might provide a rent credit after the restaurant completes approved works.
Read the lease alongside any offer letter, side agreement and fit-out conditions. Establish whether the contribution is linked to entering the lease, completing particular work or delivering something separately for the landlord.
Look at the eligible expenditure as well. The agreement may cover fixed improvements but exclude movable kitchen equipment, furniture or design fees. A maximum contribution is not necessarily the amount the restaurant will ultimately receive.
Prepare a short summary of the terms, including the amount, conditions, payment timing and any repayment clauses. This gives finance a clear basis for reviewing the transaction before entries are posted.
Confirm Which Reporting Framework Applies
The accounting explanation needs to match the restaurant company’s financial reporting framework. For entities applying SFRS(I) 16 or FRS 116, the relevant lease model corresponds to IFRS 16. An eligible entity using the Singapore Financial Reporting Standard for Small Entities may follow different requirements.
Under the full lease model, a lessee generally recognises a right-of-use asset and lease liability, subject to the applicable exemptions. The right-of-use asset represents the right to use the premises, which is distinct from separately recognised renovation assets.
Avoid copying an old example that simply spreads an incentive through a rent-expense account without checking the framework. Equally, do not assume that every small restaurant uses the small-entities framework.
State the framework and the basis of the assessment in the accounting file. This article focuses on the full lease model and ordinary restaurant fit-out arrangements.
Determine Whether the Contribution Is a Lease Incentive
Lease incentives include payments associated with a lease and reimbursement or assumption of a lessee’s costs. Where the landlord contributes towards improvements that are the restaurant’s assets as part of the lease arrangement, lease-incentive treatment may be appropriate.
The result can differ where the restaurant is arranging work on an asset controlled by the landlord. Who signs the contractor’s invoice is relevant evidence, but it does not answer every question about the underlying asset and arrangement.
Document the nature of the works, who directs them and which party obtains the relevant benefits. Include the terms governing use during the lease and what happens when the lease ends. An eventual transfer of fixtures to the landlord does not, by itself, establish the entire accounting conclusion.
Where the project includes different categories of work, assess them separately. A single contribution agreement may cover items that should not all be treated identically.
Understand Where the Incentive Enters the Lease Calculation
Under the full lease model, incentives received at or before commencement reduce the cost of the right-of-use asset. Fixed incentives receivable are reflected in measuring the remaining lease payments used for the lease liability.
The payment’s timing therefore matters. Finance needs to distinguish an incentive already received from an amount receivable later and apply the relevant measurement requirements consistently. The same benefit should not be deducted twice.
Conditional or uncertain reimbursements need closer assessment. A promise to reimburse “up to” a stated amount after approval is not necessarily equivalent to an unconditional fixed incentive at commencement.
Retain the calculation and its assumptions. If the contribution is settled after the initial lease entries, reconcile the receipt to the original treatment rather than automatically recording it as new income when the bank account is credited.
Keep the Renovation Asset Separate From the Incentive
A landlord’s contribution does not remove the need to assess the renovation expenditure itself. The restaurant should identify which costs qualify as assets and which should be expensed under the applicable requirements.
For qualifying property, plant and equipment, cost includes expenditure directly attributable to bringing the asset to the location and condition needed for its intended operation. General opening promotions, staff training and routine operating costs do not become renovation assets merely because they are incurred before opening.
Separate kitchen equipment, furniture and leasehold improvements where their characteristics justify different asset records. A contractor’s combined invoice may need a supporting breakdown.
Where the landlord’s payment is a lease incentive, it should not automatically be deducted from those renovation assets. The fit-out and the right to use the premises are different accounting components, even though the cash contribution helps fund the same opening project.
A Simplified Example Shows the Difference
Assume a restaurant incurs S$300,000 on fit-out that qualifies as its own property, plant and equipment. The landlord pays S$60,000 at lease commencement, and the documented assessment concludes that the amount is a lease incentive.
Also assume the present value of the remaining rent payments is S$500,000. For simplicity, there are no other lease prepayments, initial direct costs or restoration adjustments, and taxes are excluded.
In this example, the initial lease liability is S$500,000. The right-of-use asset is S$440,000 after deducting the S$60,000 incentive received. The qualifying fit-out remains separately recorded at S$300,000.
The contribution is not immediately recognised as S$60,000 of operating income. Nor is it automatically used to reduce the fit-out asset to S$240,000. Its effect is reflected through the lease accounting.
These figures illustrate one specific arrangement. A contribution receivable later, a conditional reimbursement or work performed for the landlord would require an assessment of its own terms rather than reuse of these entries.
Check the Important Dates Independently
The date the lease is signed, the date the premises become available and the restaurant’s first trading day may differ. Each has a different role in the accounting review.
Lease commencement is generally when the lessor makes the underlying asset available for use by the lessee. This may occur during the fit-out period, before the restaurant serves its first customer. A rent-free period does not automatically postpone commencement.
Separately, depreciation of qualifying renovation assets begins when they are available for their intended use. Different items may become ready at different times, so the opening date should not replace a review of the actual facts.
Prepare a timeline supported by handover records, contractor completion documents and asset information. This makes it easier to explain the dates used in the lease and fixed-asset schedules.
Support the Useful Lives of the Improvements
A substantial fit-out can remain physically usable for many years, but the restaurant’s expected access to the premises affects how long it can benefit from non-removable improvements.
Assess useful lives alongside the lease term and relevant renewal or termination considerations. Do not assume that management’s hope to remain indefinitely is enough to support a long depreciation period.
Movable equipment may need a different assessment from work that cannot economically be removed. A commercial oven that can be transferred to another outlet is not necessarily comparable with fixed flooring or built-in works.
Keep the reasoning proportionate to the amounts involved. The objective is to support the period over which the restaurant expects to use the asset, with assumptions that are consistent across the lease and renovation records.
Track Conditions Before Assuming the Full Amount Is Recoverable
Some contributions require submission of paid invoices, completion certificates or evidence that approved specifications were followed. The restaurant should maintain a claim schedule showing what has been submitted, accepted and paid.
Distinguish eligible spending from the total project budget. If the landlord excludes certain items, the restaurant may receive less than the headline contribution even though it spends more than expected overall.
Record unresolved matters clearly. An email requesting additional documents is different from written confirmation that the claim has been accepted. Finance needs the actual status when assessing the appropriate balance at the reporting date.
If a contribution becomes disputed or repayment conditions may be triggered, review the accounting implications promptly. Do not leave the original treatment unchanged merely because the payment was previously expected or received.
Why the Auditor May Ask for More Than the Bank Receipt
The bank receipt establishes that cash arrived, but it does not explain the payment’s purpose or how it should be reported. The audit team needs evidence supporting management’s classification, measurement and timing.
Prepare the signed lease, contribution terms, fit-out invoices and payment records together with the lease calculation. Include the fixed-asset schedule and any correspondence that changes the original agreement.
Where the landlord paid a contractor directly, provide the documents explaining whose obligation was settled and which works were covered. Direct payment does not make the transaction irrelevant to the restaurant’s accounts.
A brief management assessment can connect these documents. Explain the conclusion, identify the important terms and show how the resulting entries reconcile to the financial statements. This is more useful than submitting an unexplained folder of renovation invoices.
Keep Cash Planning Distinct From Reported Profit
The contribution can reduce the amount the restaurant needs to fund, even where it is not immediate income. That cash benefit remains commercially important.
Prepare an opening-project cash schedule showing contractor payments and the expected contribution receipt. A reimbursement received after completion may leave the restaurant funding the full renovation temporarily, despite the lower eventual net outlay.
Avoid treating a reduction in the accounting cost of the right-of-use asset as cash available for payroll or suppliers. Accounting balances and payment schedules answer different questions, and both need to be understood.
Management should also distinguish the contribution from refundable deposits and unrelated landlord payments. Combining them under one general account can make both cash planning and year-end review harder.
Review the Records When the Arrangement Changes
Renovation projects often change after the lease is agreed. Costs increase, specifications are revised and the landlord may approve additional support or substitute a rent credit for a cash payment.
Send those changes to finance when they occur. An updated commercial agreement may require a new accounting assessment, and the correct response depends on the nature and timing of the change.
Do not simply add a later payment to the original incentive calculation without reviewing the circumstances. Equally, do not assume a later receipt must be other income because the initial lease schedule has already been prepared.
Maintain version-controlled schedules and retain approval evidence. A clear record of changes helps management explain why the final accounting differs from the opening budget.
Prepare for the Audit Before the Fit-Out File Is Closed
Once the restaurant opens, attention naturally shifts to customers, staffing and daily operations. The people who negotiated the lease or managed the fit-out may move to another project, making outstanding accounting questions harder to resolve.
Complete the contribution assessment while the supporting information is readily available. Confirm that the lease schedule, renovation register, claim records and bank entries are consistent. Identify unresolved balances and assign responsibility for following them up.
Royal Premier PAC provides financial statement audit services. Restaurant companies planning for their audit can support the process by sharing significant lease incentives and renovation arrangements early, together with management’s accounting assessment.
For businesses considering auditing services Singapore firms provide, the key question is what the landlord’s payment represents under the agreement. Establishing that first allows the contribution, renovation assets and lease balances to be recorded on a consistent basis, while giving management a clearer view of the restaurant’s opening investment.
Recent Comments